Debt assigned in divorce decree is one of the most misunderstood protections in a settlement — and one of the most expensive to learn about at the wrong moment. This is a composite illustration drawn from patterns I have seen repeatedly in my work with divorcing women in Texas. Details have been changed to protect privacy.
The Setup
She got the house. That part was clear in the decree.
She was awarded the marital home in a high-conflict North Texas divorce. The settlement gave her the property, assigned her the responsibility for the primary mortgage, and — on paper — assigned the HELOC to her ex-husband. He had taken out the home equity line of credit years earlier. He was the one who had been making the payments. The debt was assigned in divorce decree – the decree said it was his.
She was relieved. She had the house, she had income, and she had a clear plan: get through the final stages of the divorce, get the refinance done, and get his name off the mortgage.
What she did not know — what no one told her until it was already a problem — was that the decree had no authority over the lender.
Despite Debt Assigned in Divorce Decree –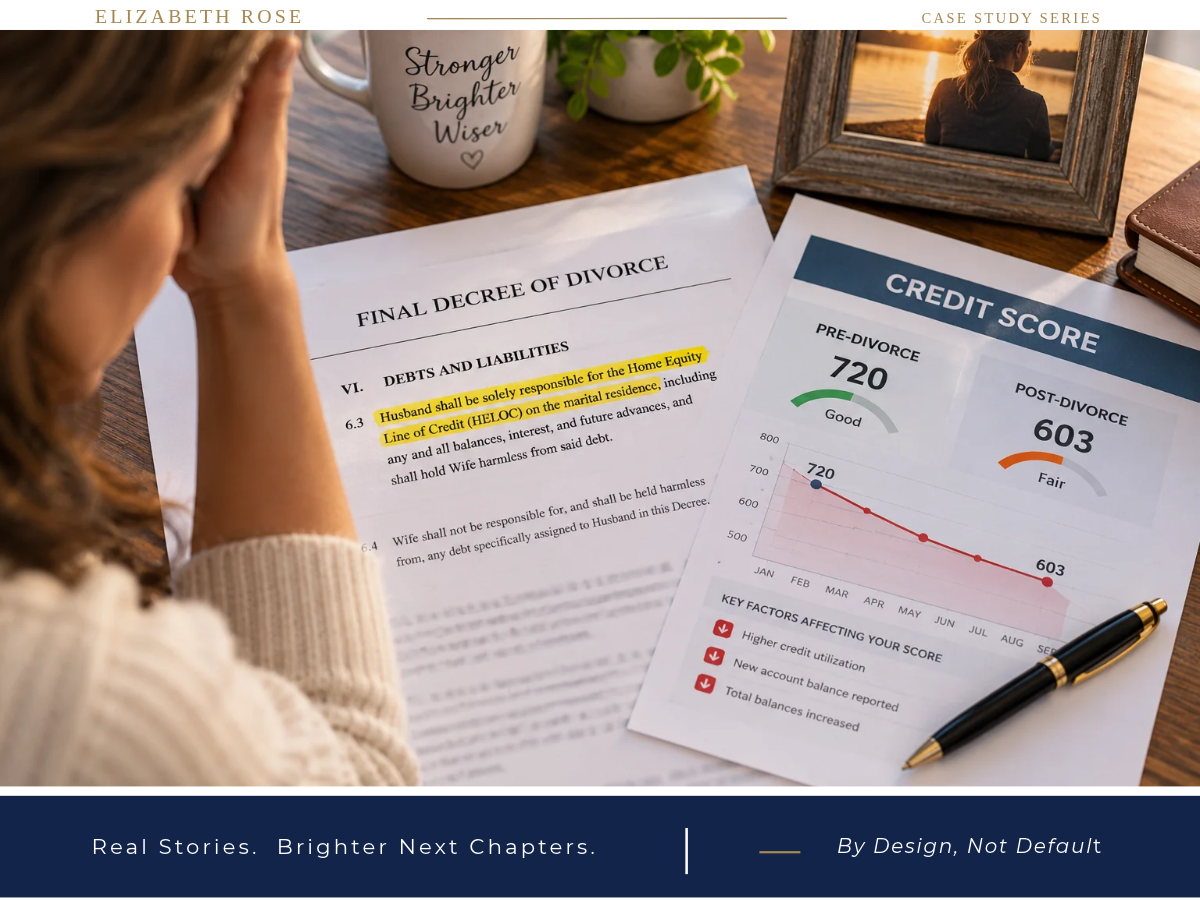
A divorce decree is a legally binding agreement between two spouses. It is not a contract with a mortgage company or a credit reporting agency.
When both names are on a loan — whether that is the primary mortgage or a HELOC — both parties remain liable to the lender until the loan is paid off, refinanced out of one party’s name, or legally assumed. The decree can require your ex-spouse to pay. It cannot force the lender to release you from the obligation if he does not.
This distinction is not a technicality. It is the mechanism by which a stopped payment on a debt “assigned to him” becomes a derogatory mark on her credit report.
Within a few months of the decree being finalized, her ex-husband stopped making payments on the HELOC. He apparently didn’t care if it hurt his credit. And it seemed he was sending a message. The reason does not matter for her credit report. What matters is that the account went delinquent — and both names were still on it.
She did not find out until she applied for the refinance.
What the Application Revealed
The refinance underwriting pulled her credit. The HELOC showed multiple missed payments. The account was past due. Her credit score had dropped significantly from where it had been at the start of the divorce process.
She could not refinance. Not because of her own payment behavior. Not because of her income. Not because of anything she had done or failed to do. But because a debt that the decree said was his was reporting on her credit as though it were hers — because legally, with the lender, it still was.
The options at that point were limited and none of them were fast.
When a past due takes place on an installment loan, or a revolving credit card account, your credit takes a hit. But, unlike with a mortgage or HELOC, you can bring it current and as long as your credit score and other factors are within guidelines, you can proceed with home financing. Mortgages and HELOC’s are treated differently. If you have a late payment on these, you have to wait – 12 months in most cases – before you can proceed with home financing.
She could attempt to force compliance through the courts — a process that takes time and money and does not necessarily produce a payment in the meantime.
She could bring the HELOC current herself and absorb the payments he was supposed to be making.
Or she could wait — and watch the derogatory marks accumulate while she stood on the sideline of her own financial life.
She chose to bring it current and take over the payments. It was not the outcome she had planned for. It was the only path that gave her control over her own timeline.
The Twelve-Month Clock
Mortgage lenders require a clean payment history on all obligations before approving a refinance. Once a derogatory item appears on a credit report, it does not simply disappear when the account is brought current. The record of the missed payments remains.
What she needed was twelve consecutive months of on-time payment history — on both the mortgage and the HELOC — before a refinance could be approved. Not from the date she learned about the problem. From the date the account was brought current and the clock started running.
She caught up the past due balance and made every payment on time. She monitored her credit. She documented everything.
Twelve months later, she was close. The derogatory history had aged. Her score had recovered. And she was preparing to sit down with a mortgage professional to assess whether the refinance was finally within reach.
What She Is Navigating Now
She is not done yet — and this is where her story sits right now.
She spent the better part of a year making payments on a debt assigned in the divorce decree to her ex-husband. She lost access to the refinance she needed during a window when rates were more favorable. She is now approaching the refinance in a higher-rate environment, on a timeline she did not choose, with a cost that was never part of her plan.
The house is still hers. Her credit is recovering. And she is doing the work to get to the close.
But the financial cost of what happened — the months of HELOC payments, the delayed refinance, the rate environment she is refinancing into now — is real. And none of it was caused by anything she did wrong.
What was missing was a conversation about what the decree could and could not protect her from before it was signed.
What the Decree Should Have Addressed
When a joint debt is assigned to one spouse in a divorce decree, the decree needs to do more than name who is responsible. It needs to include protections that account for the lender’s position — which is independent of what the two spouses have agreed to.
Language requiring the responsible spouse to refinance or pay off the account within a defined timeframe. Language that allows the other spouse to cure a default and seek reimbursement. Language that addresses what happens to the property if the assigned debt creates a lien problem or a refinance barrier.
An attorney drafts the decree. A Certified Divorce Lending Professional evaluates whether what the decree says is actually executable in the mortgage world — because those are not always the same analysis.
In this case, no one evaluated the HELOC language before the decree was final. The problem was discovered at the refinance application, not at the negotiating table — which is the most expensive place to learn it.
RELATED READING
What Credit Score Do I Need to Keep the House After Divorce?
What Makes a Divorce Decree Mortgage-Ready in Texas?
Pay Off Debt First — or Save for a Down Payment After Divorce?
House Expenses After Divorce — The Full Cost Every Woman Needs to See Before She Decides
She Had Enough Equity to Keep the House. She Didn’t Have Enough Income.
She did everything right after the problem surfaced. She brought the account current, made every payment, monitored her credit, and waited twelve months. None of that would have been necessary if the decree had been written differently.
If there is a joint account in your settlement being assigned to your spouse — without a payoff timeline or a cure clause attached — the Before You Sign Assessment is where we look at that language before it becomes your problem to solve.
The decree said it was his debt. The lender did not care. If there is a joint account anywhere in your settlement being assigned to your spouse — without a payoff or refinance requirement attached — this page is where you find out what that means for your mortgage before the decree is final.
Elizabeth Rose is a Certified Divorce Lending Professional and licensed mortgage professional serving women throughout Texas with 29+ years of experience in real estate, mortgage, and financial services. She is also a retirement strategies and annuities strategist, and the author of Sister, Own Your Finances. Elizabeth helps women navigate the financial decisions that carry the most weight — by design, not default. NMLS# 252686 | NPN# 19058858