She gave up the marital home in divorce. That sentence sounds like a loss. What it actually was — once the full picture was on the table — was a decision that changed what the rest of her financial life looked like.
This is a composite illustration drawn from patterns I have seen repeatedly in my work with divorcing women in Texas. All figures are hypothetical and illustrative. Details have been changed to protect privacy.
The Setup
She was fifty-seven years old. She had been married for twenty-eight years. The marital home had been part of her life for most of that — the house she raised her children in, the address she had given for over two decades, the place that felt like hers even when everything else in the marriage had stopped feeling that way.
When the divorce became real, keeping the house was the first thing she said she wanted.
The numbers were significant. The home was valued at $575,000. The mortgage balance was $225,000. That left $350,000 in equity — a number that felt like security.
The rest of the marital assets included approximately $310,000 in retirement accounts and $90,000 in liquid savings. Total net assets: approximately $750,000, excluding taxes, transaction costs, and other liabilities.
On paper, the picture looked strong. In practice, the question was not what the assets were worth. It was what her financial life would look like on the other side of this decision.
What Keeping the House Would Have Actually Required
She earned $67,000 annually — approximately $5,583 per month gross. That income had been part of a two-income household for twenty-eight years. Now it was the only income.
Keeping the marital home meant refinancing the mortgage into her name alone — removing her spouse from the loan and paying out his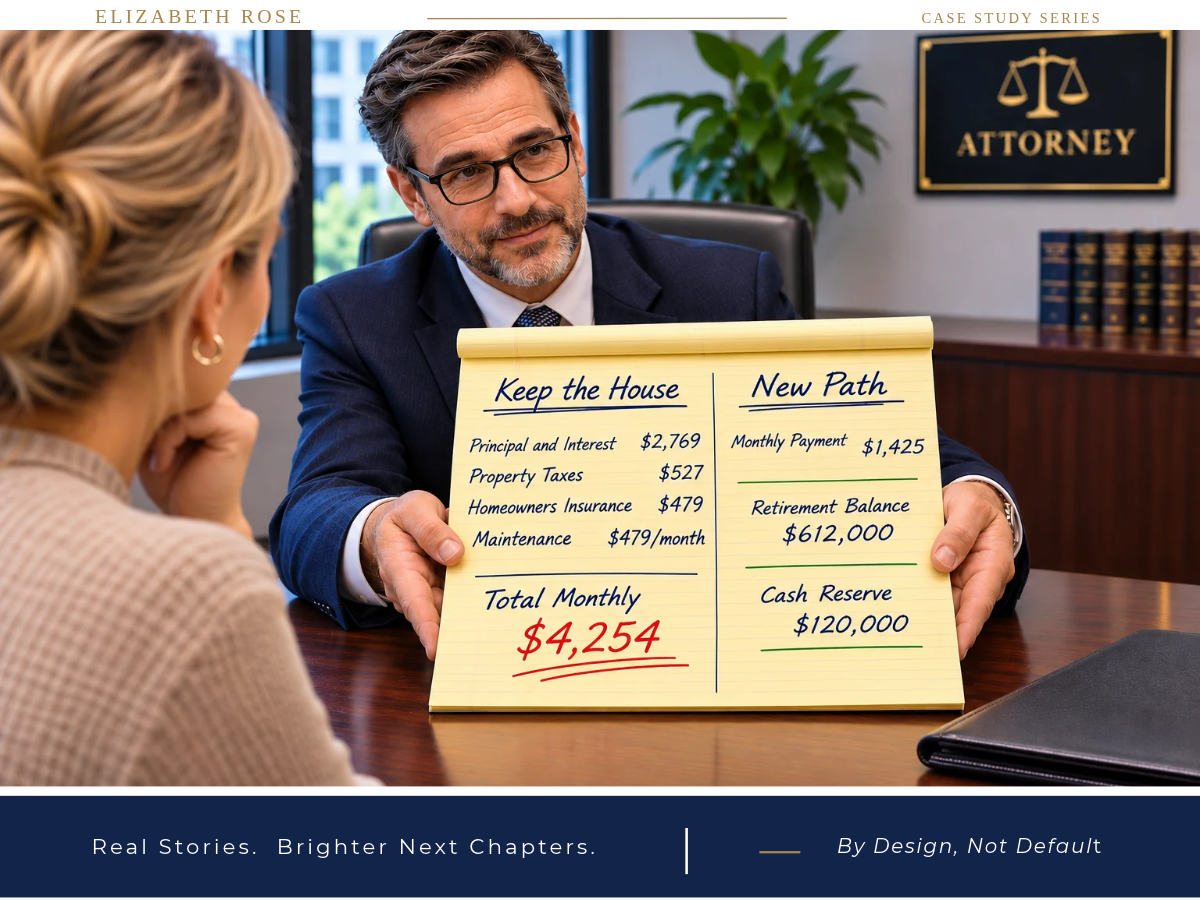 equity share. At $350,000 in equity, a 50/50 division would require her to refinance for approximately $400,000 (the existing $225,000 balance plus a $175,000 equity buyout). That assumes an equal split, which is an illustration only — actual settlement terms vary.
Monthly cost of keeping the marital home — illustrative:
— Principal and interest on $400,000 at 7.4%: $2,769
— Property taxes (est. 1.1% of $575,000): $527/month
— Homeowners insurance (est. 1%): $479/month
— Estimated maintenance reserve (1% of value annually): $479/month
— Total estimated monthly housing cost: $4,254
Against her $5,583 gross income, that housing cost alone represented 76% of her gross monthly earnings — before a single other expense.
She would not have qualified for the refinance. And even if she had found a way to structure it, the payment would have consumed every dollar she made and left nothing for groceries, transportation, healthcare, or rebuilding any financial foundation at all.
The house was not security. At her income level, it was a financial commitment she could not sustain.
Instead, She Gave Up the Marital Home in Divorce
Rather than treating the house as the most valuable asset in the settlement, she started asking a different question: what combination of assets would give her a housing situation she could actually afford, retirement savings she did not have to touch, and enough liquid cash to start her next chapter without being immediately financially fragile?
The settlement discussions explored the alternative if she gave up the house in divorce. Instead, her spouse would retain the marital home. She received a negotiated allocation of the retirement accounts and liquid savings. The retirement assets — transferred via QDRO to avoid immediate taxation and penalty — remained invested. The liquid savings became the foundation for her next housing transition.
Important note: This is not a legal, tax, or financial planning recommendation. The actual tax treatment of retirement assets distributed in divorce depends on the account type, the transfer method, age, and other factors. A QDRO distribution from a qualified plan has different rules than an IRA transfer. Anyone in this situation should work with a CPA and a qualified financial advisor before making decisions about retirement assets in a settlement.
What the Numbers Showed on the Other Side
Hypothetical post-divorce outcome:
New home purchase price: $265,000
Down payment from liquid savings: $55,000
Loan amount: $210,000
Estimated P&I at 7.4%: $1,453/month
Property taxes (est. 1.1% of $265,000): $243/month
Homeowners insurance (est. 1%): $221/month
Total estimated PITI: $1,917/month
Against her $5,583 gross monthly income, that housing cost represents approximately 34% of gross — within the range a lender would qualify, and within a range that left meaningful room for the rest of her financial life.
Liquid savings remaining after down payment and estimated closing costs: approximately $20,000–$25,000. Not a full six-month reserve yet — but a starting point, not a zero.
Retirement allocation retained: $310,000 — untouched and invested for future needs.
She did not receive more assets in this scenario than she would have if she had kept the house. She received a different combination of assets — ones that matched her income, her housing needs, and her long-term financial security in a way the marital home never could have.
What the Tradeoffs Actually Were
The case for keeping the house is real. It deserves honest examination, not dismissal.
The house had a mortgage rate from a different rate environment — potentially lower than what she would qualify for today on a new purchase. She had an emotional connection to the property that was genuine and significant. The neighborhood, the school district, the neighbors — none of that transferred to a new address.
But the financial tradeoff was not close:
— The marital home required a housing cost equal to 76% of her gross income.
— The alternative required 34%.
— The marital home refinance would have consumed most of her liquid savings at closing and left no cash reserves.
— The alternative left $20,000–$25,000 in accessible savings after closing.
— The marital home paymnet left no margin to contribute to retirement savings going forward – a 75% housing cost ratio leaves nothing.
— The alternative left a monthly payment that allowed her to resume contributing, with $310,000 in retirement assets untouched and invested.
The house was not the most valuable thing she could have kept. The financial flexibility on the other side of letting it go was.
She gave up the marital home in divorce. What she kept was a housing payment she could sustain, a cash reserve to absorb the unexpected, and room to rebuild rather than scramble.
What This Case Study Is Really About
The asset that feels most like security is not always the asset that provides it.
Home equity is real wealth. But it is not liquid. It does not pay the electric bill. It does not fund the emergency reserve. And it does not qualify for a mortgage on its own — the income does.
A settlement built around keeping the house at any cost can leave a woman financially overextended, retirement-depleted, and without the liquid savings to absorb a single unexpected expense. A settlement built around the full financial picture — housing cost as a percentage of income, retirement assets as long-term security, liquid savings as the foundation for stability — often looks very different.
The question is not which asset has the most value on paper. The question is which combination of assets creates the most sustainable financial life on the other side of the decree.
If you are in the settlement process and trying to understand what different asset divisions actually mean for your housing qualification and long-term financial picture — that is the analysis the Before You Sign Assessment is designed to run before anything is finalized.
RELATED READING
How Divorce Settlement Decisions Affect Your Ability to Keep or Buy a Home
House Rich, Cash Poor After Divorce — Why Home Equity and Liquid Assets Are Not the Same Thing
One-Income Mortgage Qualification After Divorce — What the Lender Actually Looks At
Cash Reserve After Divorce — How Much You Actually Need and Why It Cannot Wait
How Spousal Support Income Qualifies for a Mortgage After Divorce
She gave up the marital home in divorce. That decision was not made out of defeat — it was made with a clear view of what the numbers actually required and what her financial life needed to look like on the other side.
The settlement that serves you best is not the one that keeps the most familiar asset. It is the one built around income, housing cost, long-term security, and what is actually sustainable when the decree is signed and the support system of the marriage is gone.
If you are navigating this decision and want to understand what the numbers mean for your specific situation — before the terms are locked in — the Before You Sign Assessment is where that analysis happens.
Women across Texas who are figuring out the mortgage side of their settlement — what qualifies, what the costs actually look like on one income, and what the decree needs to say to make the housing plan work — find the answers they need here before they sign anything.
Elizabeth Rose | Certified Divorce Lending Professional NMLS# 252686 | Licensed in Texas
This scenario is a composite illustration for educational purposes only. It does not constitute legal or financial advice. Names and details are fictional.