Downsizing after divorce looked like giving up to Angela when she sat down to run the numbers. Everyone around Angela assumed she would fight for the house. So did she. Five years later, she says the numbers changed her mind, not anyone’s advice.
Downsizing after divorce was not the outcome she wanted. It was the one that left her the most room.
The Decision She Almost Made
Angela’s marriage ended after twelve years. She had two kids and a home worth $315,000 with a $195,000 mortgage. On her income alone, she could qualify to refinance, barely. Her debt-to-income ratio would land at 48%, right at the edge of what most lenders approve, with no room for a medical bill or a car repair.
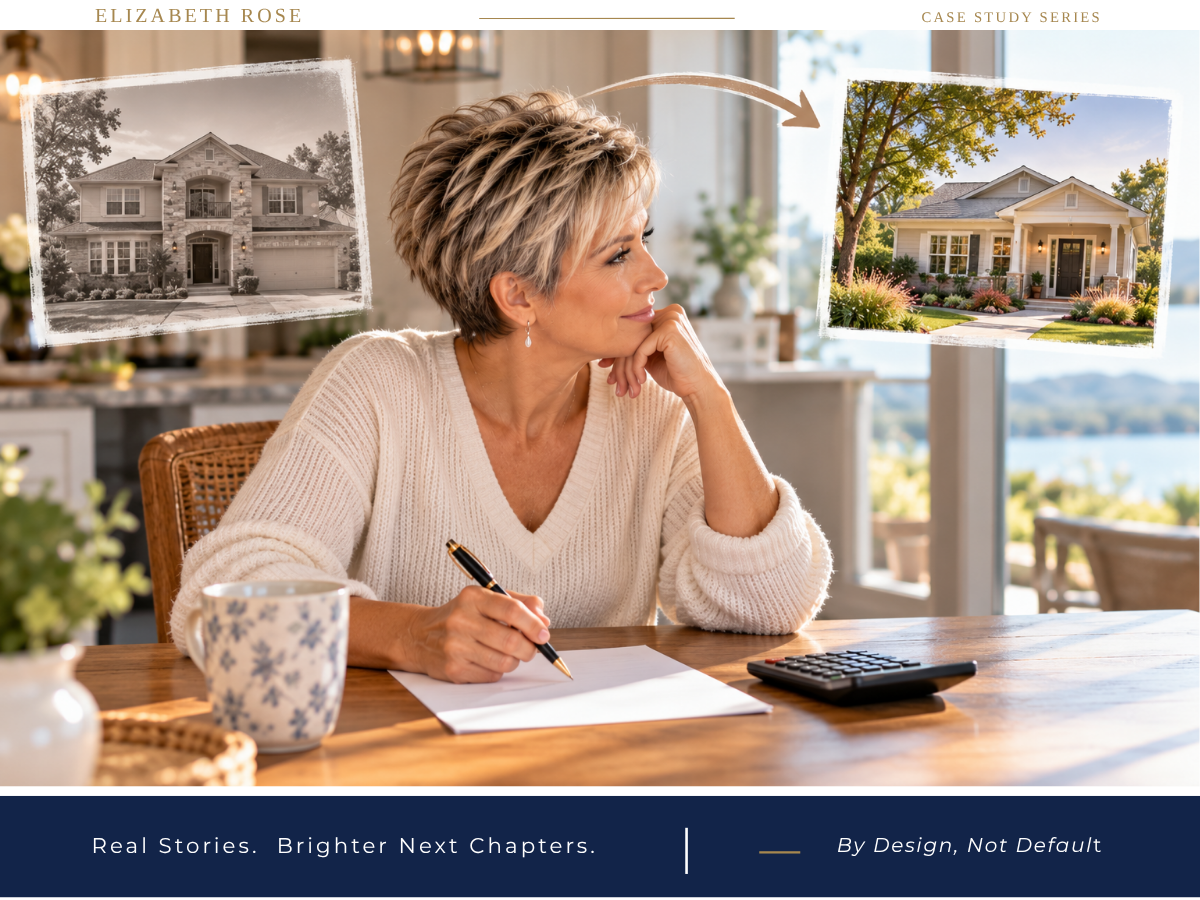
Downsizing after divorce was not her hearts desire. She wanted to keep the house. It was the only home her kids had known.
So we ran the whole picture: property taxes, insurance, upkeep on a fourteen-year-old house, and a budget with almost no cushion. The numbers told a different story than her instinct did.
Angela chose to sell. She and her kids moved into a rental for fourteen months.
What Fourteen Months of Renting Built
The rental was not a consolation prize. It was the foundation.
Her share of the sale proceeds, roughly $48,000 after closing costs, stayed documented and untouched. She rebuilt her credit without carrying a mortgage sized for two incomes. And her new job’s income built the two-year history that lenders can fully credit.
Eighteen months after the divorce, Angela bought a smaller home for $240,000 with 15% down. Her total debt-to-income ratio came in at 34%. Not 48%.
Why Downsizing After Divorce Built More Than Keeping the House
Five years out, the smaller home has appreciated to roughly $290,000. Between paying down principal through her regular monthly payments, appreciation and her original down payment, she holds about $95,000 in equity. Her emergency fund exists. Her retirement contributions never stopped.
The version of the story where she kept the original house has no ending she can picture clearly. Every month would have been tighter than the last. A roof repair or a slow season at work would have forced a decision under pressure, instead of one made with clarity.
Downsizing after divorce was the right decision for Angela.
What This Downsizing After Divorce Scenario Teaches
The choice that feels right in the moment, keeping the house and protecting the version of normal your kids remember, is not always the one that builds the most secure life five years out.
The questions worth sitting with before that decision is final:
– What does your full financial picture look like one year after the divorce, not just on the day you sign?
– If renting or a smaller home is the bridge to a stronger position, what does that bridge cost, and what does it build?
– Five years from now, which choice leaves more room for savings, for stability and for the unexpected?
A house is not just an asset in a settlement. It is the financial ground you will stand on for years afterward. That ground deserves the same scrutiny as everything else on the table.
If you’re weighing whether to keep, sell, or downsize after divorce, I want to help you see five years down the road — not just the decision in front of you.
No pressure. No rush. Just clarity.
Related Reading
Should I sell the House in a Texas Divorce – or Keep It?
Can I Afford to Keep the House in a Texas Divorce?
Keeping the House After Divorce – Financial Decision or Emotional One?
Selling the House in a Texas Divorce – What You Need to Know
Buying a Home After Divorce – Documents You Need to Qualify
Credit Improvement After Divorce – How to Rebuild and What Actually Works
Buying a Home After 50 in Texas – What Changes
Elizabeth Rose | Certified Divorce Lending Professional NMLS# 252686 | Licensed in Texas
This scenario is a composite illustration for educational purposes only. It does not constitute legal or financial advice. Names and details are fictional.